
Last Updated: November 2, 2026
Quick Summary
Storage insurance is worth it when your home contents policy stops covering goods kept in a commercial facility, which typically happens once you no longer live at the insured address or the goods exceed the policy’s time limit. A separate storage insurance policy covers events like fire, theft, storm damage and vandalism, but excludes mould, gradual deterioration and vermin.
- Home contents cover usually ends once goods sit in storage beyond the policy’s time limit.
- Replacement value pays what it costs to buy the item new today, while depreciation pays its current worth.
- Most policies default to depreciated value unless you specifically select replacement cover.
- Photograph each item before packing and keep a cloud copy of your inventory as claim evidence.
- Report the loss to the facility and police, then notify your insurer within the policy timeframe.
Table of Contents
- What Storage Insurance Actually Covers (and What It Doesn’t)
- Contents Insurance in Storage: Does Your Home Policy Follow Your Belongings?
- Storage Insurance Exclusions You Need to Read Twice
- Insuring Furniture in Storage: Replacement Value vs Depreciation
- How to Value Your Belongings Before You Sign a Storage Agreement
- Storage insurance claims: A Step-by-Step Walkthrough
- Book Your Unit and Get Your Cover Sorted Before Move-In
- Frequently Asked Questions
What Storage Insurance Actually Covers (and What It Doesn’t)
Storage insurance is a separate policy that covers your belongings while they sit in a storage unit, away from your home. It responds when something unexpected happens to those goods, and it does not respond to everything.
Confusion about storage cover is common. People move their furniture in, assume they’re covered, and only read the fine print after a problem appears.
So let’s be clear about the basics before anything else.
The events a policy responds to
Most storage policies list the events they cover. These typically include:
- Fire and smoke damage
- Theft or burglary
- Storm and water damage
The wording differs between insurers. Always check the product disclosure statement, because that document is the contract.
Here are the events a typical storage policy responds to, and the wording that decides whether a claim is paid.
| Event or term | What the article says |
|---|---|
| Fire and smoke damage | Typically listed as covered |
| Theft or burglary | Typically listed as covered |
| Storm and water damage | Typically listed as covered |
| Vandalism | Typically listed as covered |
| Accidental damage | Covered during a covered event |
| Product disclosure statement | The contract; wording differs between insurers |
Contents Insurance in Storage: Does Your Home Policy Follow Your Belongings?
Sometimes. Many home contents policies cover items temporarily removed from the home, but “temporarily” is doing a lot of work in that sentence. The cover usually runs out once the goods sit elsewhere for an extended period, or once you’ve moved out entirely.
This is the trap. People downsize, renovate, or relocate and leave furniture in storage for months. Their home policy quietly stops applying, and they never notice.
When the home policy stops covering you
Cover typically ends when:
- You no longer live at the insured address
- The goods have been in storage beyond the policy’s time limit
- The storage facility isn’t on the insurer’s approved list
Ring your insurer and ask one direct question: “Does my contents insurance cover goods in a commercial storage facility, and for how long?” Get the answer in writing.
Storage Insurance Exclusions You Need to Read Twice
Exclusions are where claims die. A policy might cover fire and theft but exclude the exact thing that damages your goods. The wording that matters is in your product disclosure statement (PDS), that document is the contract, and the summary a facility hands you is not.
Common exclusions include:
- Mould and mildew, which is a real risk in humid or poorly ventilated units
- Gradual deterioration, such as rust, warping, or fading over time
- Vermin and insect damage, including rodent droppings and insect nests
How to read the exclusions in a PDS
PDS documents can run to many pages, and the exclusions are not always in one place. A practical approach is to search the PDF for four words: exclude, not covered, limitation, and condition.
Watch out: a policy may cover theft but exclude theft where there is no visible sign of forced entry. If you want to understand how CCTV at a facility can affect premiums, that guide explains the risk factors insurers weigh.
Environment and packing exclusions
Storage environment matters more than most people expect. A standard, non-climate-controlled unit in a humid climate carries a higher mould risk, and insurers increasingly treat mould as a maintenance issue rather than a sudden event.
Packing exclusions work the same way. If you want a deeper look at what theft and damage cover actually responds to, read our guide on whether storage insurance covers theft and damage.
The exclusions that catch people most often
Some exclusions come up often in storage claims. These include mould and mildew, mysterious disappearance, goods that are simply missing with no evidence of theft, and damage caused by the goods themselves, such as a leaking bottle of cleaning product ruining a sofa.
If any of those three risks applies to what you are storing, ask the insurer in writing whether cover is available and at what sub-limit. A written answer is far more useful at claim time than a verbal assurance at the counter.
Insuring Furniture in Storage: Replacement Value vs Depreciation
This is the gap most people miss, and it costs them at claim time.
Replacement value pays what it costs to buy the item new today. Depreciation pays what the item is worth now, after years of use.
The catch? Replacement cover usually costs more in premium. Depreciated cover is cheaper upfront but leaves you short when you claim.
Our take: if your furniture is older and low in value, depreciated cover is fine.
Book Online in 3 Minutes & Get 50% Off Instantly →
Why climate control changes the risk picture
Climate-controlled units hold temperature and humidity steady. That reduces the mould, warping, and rust risks that standard units carry in humid conditions. It doesn’t remove them, but it lowers the odds.
For timber furniture, leather, artwork, or electronics, the difference is real. If you’re weighing the trade-off, our comparison of climate-controlled versus standard storage breaks down the risk and cost side by side.
How to Value Your Belongings Before You Sign a Storage Agreement
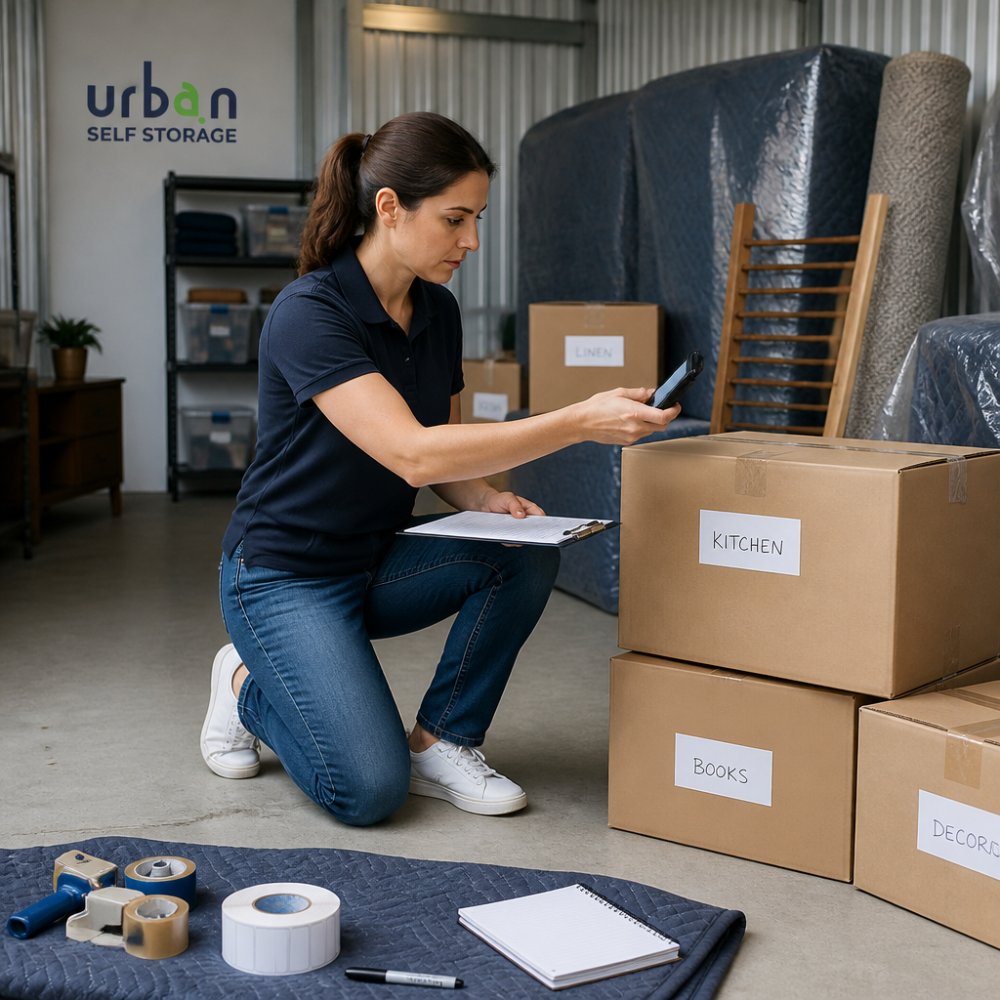
Walk through your home room by room and write down what you are storing. Then photograph everything. This inventory list is your proof of ownership, and without it, a claim becomes a negotiation you will likely lose.
Build a digital inventory that survives a claim
Most guides tell you to make a list. Few explain what a list that actually works at claim time looks like. A claim-ready inventory has four layers, and each one answers a different question the assessor will ask.
- A room-by-room list with each item, its approximate age, and the price you paid where you remember it. This answers what was stored.
- Photographs of each item, taken before packing, plus a photo of the item inside its labelled box. This answers what condition it was in.
- Receipts, serial numbers, and model numbers where you have them, stored as scans or photos. This answers what it is worth.
- A short video walkthrough of the loaded unit, narrated with box numbers. This answers where it was and is the single most useful piece of evidence in a disputed claim.
Keep the whole set in cloud storage, not on a phone that travels with you and not on paper inside the unit.
Replacement value versus depreciated value, how the payout is actually calculated
This is the gap most people miss, and it costs them at claim time.
The mechanism matters because most policies default to depreciated value unless you specifically select replacement cover, and replacement cover usually carries a higher premium.
A common pattern is that people insure for the purchase price and then discover the payout is calculated on current value.
In general, if your furniture is older and low in value, depreciated cover may be sufficient.
Why climate control changes the risk picture, and sometimes the eligibility
Climate-controlled units hold temperature and humidity steady. That reduces the mould, warping, and rust risks that standard units carry in humid conditions. It does not remove them, but it lowers the odds.
For timber furniture, leather, artwork, electronics, and musical instruments, the difference is real.
If you are weighing the trade-off, our comparison of climate-controlled versus standard storage breaks down the risk and cost side by side.
A quick valuation method
If you do not want to price every item individually, group your goods into three bands, high-value (electronics, instruments, artwork), mid-value (furniture, appliances), and low-value (clothing, books, kitchenware), and estimate each band. Add the bands together, then add a margin for items you have forgotten. Most people underestimate their stored goods on the first pass, and the sum insured needs to reflect the total, not the amount you would like to pay premium on.
Storage insurance claims: A Step-by-Step Walkthrough
The claim process is straightforward if your paperwork is in order. Most delays come from missing proof, not from the insurer being difficult.
- Report the loss to the storage facility and the police, if theft is involved
- Notify your insurer as soon as possible, within the timeframe in your policy
- Gather your evidence: photos, inventory list, receipts, and the police report
- Request any CCTV footage from the facility before it’s overwritten
- Complete the claim form accurately, item by item
- Keep damaged goods until the insurer says you can dispose of them
- Track your claim reference and follow up in writing
CCTV footage can be genuinely useful here. Our article on whether CCTV footage can support your storage insurance claim explains how it helps and what it can’t prove.
The Australian Securities and Investments Commission regulates general insurance and publishes guidance on how claims should be handled.
Book Your Unit and Get Your Cover Sorted Before Move-In
Here’s the honest version: insurance is boring until the day you need it. Then it’s the only thing that matters.
Sort your cover before the first box goes in. Confirm what your home policy does, buy a storage policy if it leaves a gap, and photograph everything you store.
When you’re ready, see our unit prices and pick the size that fits your goods, whether that’s furniture storage in Bunbury for a renovation or short and long term storage in Bunbury WA while you relocate.
Frequently Asked Questions
Are belongings covered by home insurance while they are in storage?
Sometimes, but not automatically. Many home contents policies limit cover for items kept at a location other than your home address, and self-storage units are often treated differently from a garage or shed. Some insurers require you to list the storage address, some cap the total value covered, and some exclude it entirely once the goods have been there for an extended period. Read your product disclosure statement or call your insurer before you move anything in, and ask specifically whether theft from a storage unit is included.
What is usually excluded from storage insurance?
Common storage insurance exclusions include cash, jewellery and watches above a stated limit, collectibles and artwork unless specified, important documents, and items that were already damaged or poorly packed before storage. Most policies also exclude loss caused by vermin, insects, mould from damp packing, and gradual deterioration. Some exclude theft where there is no sign of forced entry. Check the exclusion clauses line by line.
How do I make a storage insurance claims?
Report the loss to the storage facility first so it can be recorded and any CCTV preserved, then notify your insurer as soon as practicable, usually within a set number of days stated in the policy. You will need your inventory list, proof of ownership such as receipts or photos, the police report number for theft, and the storage agreement. Keep damaged items until the assessor has seen them. Delays in reporting can affect whether a storage insurance claim is paid.
Should I insure for replacement value or depreciated value?
Replacement value cover pays what it costs to buy a comparable new item today, while depreciated value pays what your used item was worth at the time of loss. Replacement cover costs more in premium but avoids a shortfall when you go to refurnish. For household goods you intend to keep using, replacement value usually makes more sense. For older furniture you were planning to replace anyway, the premium difference may not be worth it.
Most people only think about storage insurance after something goes wrong, and by then the paperwork is already set in stone. Urban Self Storage makes the setup simple: advanced 24/7 CCTV surveillance, flexible short and long-term options, and a move-in process that takes under 10 minutes. Get started with Urban Self Storage and store your belongings with the cover and confidence they deserve.
